The Backbone of the Philippine Economy: How MSMEs Drive 40% of GDP and 60% of Employment
The Unseen Giants of Philippine Commerce
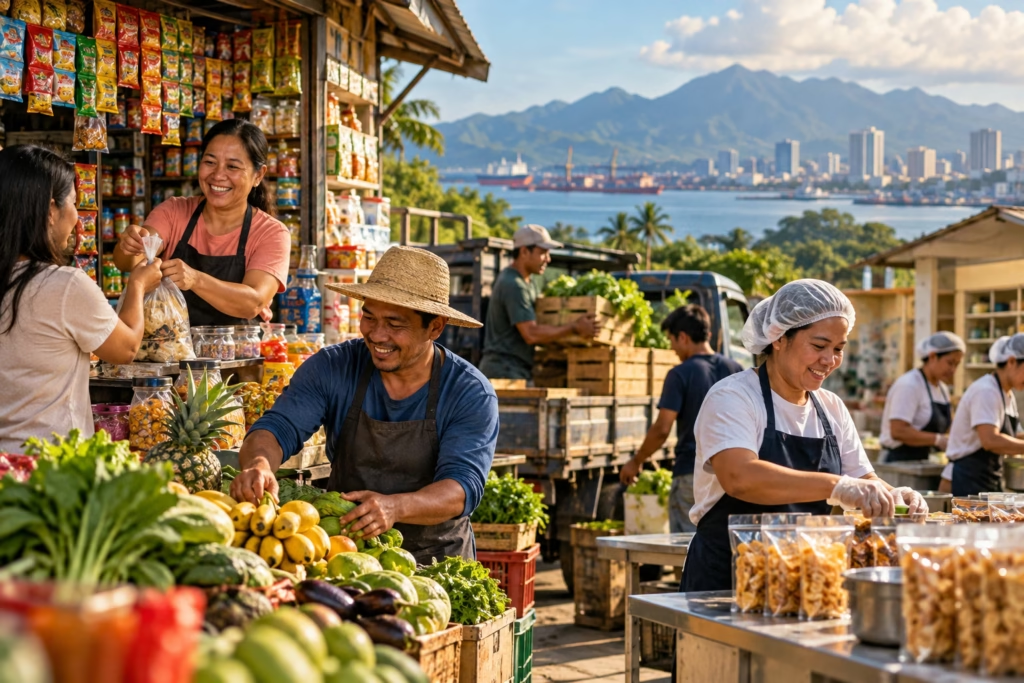
When analysts talk about the Philippine economy, they often focus on large conglomerates and foreign investments. Yet the true architects of the nation’s economic resilience are far smaller in scale—and far more numerous. Micro, small, and medium enterprises (MSMEs) account for a staggering 99.6% of all registered businesses in the Philippines, a figure that underscores their overwhelming presence in every sector of the economy.
These enterprises are not merely numerous; they are the circulatory system of Philippine commerce. According to the Asian Development Bank, MSMEs employ over 60% of Filipino workers and contribute more than one-third of the country’s gross domestic product. More recent estimates place their GDP contribution at approximately 40%, alongside roughly 25% of export revenues. This dual role—as both employer and producer—positions MSMEs as indispensable to any conversation about inclusive growth.
Beyond Metro Manila: The Regional Reach of MSMEs
The economic footprint of Philippine MSMEs extends far beyond the capital region. In Northern Mindanao alone, approximately 47,748 MSMEs operate across retail trade, food services, and manufacturing, including about 43,000 microenterprises and 144 medium enterprises. This regional dispersion is critical: it means that economic activity is not concentrated in a handful of urban centers but is distributed across provinces, municipalities, and barangays.
Moody’s Analytics economist Sarah Tan has emphasized that MSMEs have “strong footholds in trade, food and accommodation, and manufacturing”—sectors that underpin domestic demand and link households to broader supply chains. When a sari-sari store in Cebu expands its inventory or a food processor in Palawan hires additional staff, the ripple effects are felt across local supply networks.
From Survival to Scale: The Employment Multiplier
The employment impact of MSMEs is perhaps their most tangible contribution. As DTI Cebu Provincial Director Marivic Aguilar noted, “For every MSME that survives, we protect that MSME’s family, we protect jobs, and then eventually the community”. This observation captures a fundamental truth: MSMEs are not just economic units but social stabilizers.
Consider the case of Paeng-Uma Food Corporation in Bohol. What began as a modest fried chicken stand has grown into a business operating more than 100 branches across Bohol, Cebu, and Cagayan de Oro, employing nearly 200 people. The enterprise now features Bohol-made food products, strengthening market linkages for local farmers and suppliers—a textbook example of how business growth can create cascading economic benefits.
Financing the Future: The Persistent Gap
Despite their outsized contributions, MSMEs remain significantly underserved by formal financial institutions. As of end-March 2026, bank lending to MSMEs reached ₱574.8 billion, yet this represented only 4.73% of the banking sector’s total loan portfolio—less than half the 10% mandated by the Magna Carta for MSMEs. The gap is even more pronounced for micro and small enterprises, which received only 1.96% of industry loan books, far below the required 8%.
ADB Director Suhail Khan has described the Philippine financing gap as ranging from ₱67 to ₱180 billion, with over 83% of reported bank lending concentrated in Metro Manila. This geographic imbalance means that viable enterprises outside the capital region remain systematically underserved.
The Road Ahead: Policy and Promise
The Philippine government has responded with a suite of programs designed to bridge these gaps. As of June 2026, more than 94,351 MSMEs had accessed over ₱32.5 billion in loans through digital channels via the Small Business Corporation. The RISE UP Program alone has benefited 40,216 MSMEs with over ₱13.4 billion in financing.
Yet access alone is not sufficient. As Leonardo Lanzona Jr., an economics professor at Ateneo de Manila University, observed, “Banks still perceive MSMEs as relatively risky borrowers… Unless incentives are provided by the government this situation is unlikely to change”. The challenge, therefore, is not merely expanding credit but transforming the structural conditions that make MSME lending appear risky in the first place.